About MUJIThree Principles in ManufacturingAbout the Advisory BoardProduct ArchivesArchivesNewsOur BusinessesMUJI BusinessesProduct Development and RetailAccommodationsFood ServicesCommunity EngagementArchitecture and Spatial DesignOther BusinessesIDÉE BusinessesCorporate InformationMessage from the PresidentOur Corporate PurposeThe Journey of Ryohin KeikakuCorporate ProfileLocationManagementGroup CompaniesThe Ryohin Keikaku Group by the NumbersOur HistoryStore Opening DataAwardsArchivesArticlesInvestor RelationsIR NewsLatest MaterialsIR CalendarMessage to Individual InvestorsIf you Become a Shareholder...EventsShareholders Special Benefit ProgramsCompany InformationManagement PolicyCorporate GovernanceIR PolicyFinancial InformationSummary of Financial ResultsFinancial HighlightsMonthly Sales FlashCredit Ratings and BondsStock InformationBasic Stock InformationStock Price InformationShareholder StatusGeneral Meeting of ShareholdersDividends / Shareholder ReturnsAnalyst CoverageArticles of Incorporation電子公告Tax PolicyIR LibraryLatest IR MaterialsConsolidated Financial ResultsData BookFinancial Results BriefingSecurities ReportConvocation Notice and Reports of Shareholders MeetingIntegrated ReportIR Briefing SessionDisclaimerIR registrationIR FAQContact us regarding IRSustainabilityIntegrated ReportESG DataMessage from the PresidentRyohin Keikaku and SustainabilityBasic Policy and ESG Management StructureMaterial Issues and IndicatorsOur PoliciesOur Approach to Product DevelopmentTopicsSustainability NewsRespect for the EnvironmentEnvironmental ManagementResponse to Climate ChangeResource CirculationThe "Design for Circularity" Product SeriesWaste ManagementWater Resource ManagementChemical ManagementBiodiversityRaw Material ProcurementEngagement with SocietyRespect for Human RightsHuman Rights Policy and Internal FrameworkHuman Rights Due DiligenceGrievance MechanismRespect for ColleaguesHuman Capital StrategyWorkplace Safety and Employee HealthMaintaining a Positive Work EnvironmentRespect for DiversityHuman Resource Development and Career DevelopmentCo-Owned Management and EngagementBasic Policy on Harassment from CustomersSupply Chain ManagementCode of Conduct for Production PartnersMonitoring Production PartnersList of Production PartnersSupplier HotlineIndirect ProcurementCustomer Safety and Peace of MindCustomer FeedbackQuality and SafetyFood-Related Responsibilities to CustomersAs a Community Center Activities at StoresRegions and CommunitiesSocial Impact AssessmentGovernancePublic Interest and People-Centered ManagementStakeholder EngagementCorporate Governance Policy and SystemAssessment of Effectiveness of the Board of DirectorsInternal ControlComplianceRisk ManagementInformation Security and Protection of Personal InformationParticipating in InitiativesExternal EvaluationsDonations and AssistanceTopRecruitOnline StoreContactメインナビゲーションメニューを閉じるメニューを開くAbout MUJIThree Principles in ManufacturingAbout the Advisory BoardProduct ArchivesArchivesNewsOur BusinessesMUJI BusinessesProduct Development and RetailAccommodationsFood ServicesCommunity EngagementArchitecture and Spatial DesignOther BusinessesIDÉE BusinessesCorporate InformationMessage from the PresidentOur Corporate PurposeThe Journey of Ryohin KeikakuCorporate ProfileLocationManagementGroup CompaniesThe Ryohin Keikaku Group by the NumbersOur HistoryStore Opening DataAwardsArchivesArticlesInvestor RelationsIR NewsLatest MaterialsIR CalendarMessage to Individual InvestorsIf you Become a Shareholder...EventsShareholders Special Benefit ProgramsCompany InformationManagement PolicyCorporate GovernanceIR PolicyFinancial InformationSummary of Financial ResultsFinancial HighlightsMonthly Sales FlashCredit Ratings and BondsStock InformationBasic Stock InformationStock Price InformationShareholder StatusGeneral Meeting of ShareholdersDividends / Shareholder ReturnsAnalyst CoverageArticles of Incorporation電子公告Tax PolicyIR LibraryLatest IR MaterialsConsolidated Financial ResultsData BookFinancial Results BriefingSecurities ReportConvocation Notice and Reports of Shareholders MeetingIntegrated ReportIR Briefing SessionDisclaimerIR registrationIR FAQContact us regarding IRSustainabilityIntegrated ReportESG DataMessage from the PresidentRyohin Keikaku and SustainabilityBasic Policy and ESG Management StructureMaterial Issues and IndicatorsOur PoliciesOur Approach to Product DevelopmentTopicsSustainability NewsRespect for the EnvironmentEnvironmental ManagementResponse to Climate ChangeResource CirculationThe "Design for Circularity" Product SeriesWaste ManagementWater Resource ManagementChemical ManagementBiodiversityRaw Material ProcurementEngagement with SocietyRespect for Human RightsHuman Rights Policy and Internal FrameworkHuman Rights Due DiligenceGrievance MechanismRespect for ColleaguesHuman Capital StrategyWorkplace Safety and Employee HealthMaintaining a Positive Work EnvironmentRespect for DiversityHuman Resource Development and Career DevelopmentCo-Owned Management and EngagementBasic Policy on Harassment from CustomersSupply Chain ManagementCode of Conduct for Production PartnersMonitoring Production PartnersList of Production PartnersSupplier HotlineIndirect ProcurementCustomer Safety and Peace of MindCustomer FeedbackQuality and SafetyFood-Related Responsibilities to CustomersAs a Community Center Activities at StoresRegions and CommunitiesSocial Impact AssessmentGovernancePublic Interest and People-Centered ManagementStakeholder EngagementCorporate Governance Policy and SystemAssessment of Effectiveness of the Board of DirectorsInternal ControlComplianceRisk ManagementInformation Security and Protection of Personal InformationParticipating in InitiativesExternal EvaluationsDonations and AssistanceTopRecruitOnline StoreContactメインナビゲーションメニューを閉じるメニューを開く
Executive Summary: Operating revenue and profits at all levels reached record highs. Operating profit exceeded 100 billion yen for the first time.
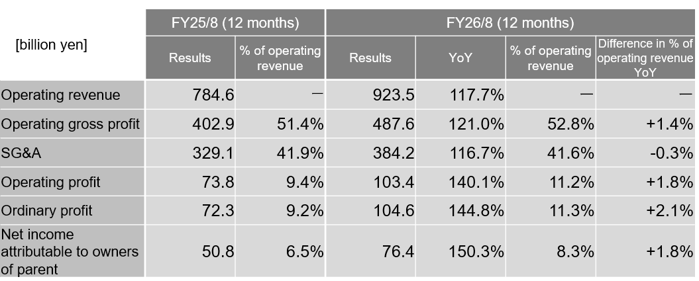
Operating revenue increased by 17.7% YoY to 923.5 billion yen, driven by an increase in the number of stores in Japan and overseas, as well as significant growth in overseas business sales.
Gross profit margin improved by 1.4pp YoY to 52.8%, driven by product cost reductions achieved through strengthening in-house production and an improvement in discount rate.
SG&A/revenue ratio improved by 0.3pp YoY to 41.6%, as sales growth outpaced the increase in SG&A.
Operating profit increased by 40.1% YoY to 103.4 billion yen, exceeding 100 billion yen for the first time. Operating profit margin improved by 1.8pp YoY to 11.2%.
Net income attributable to owners of parent increased by 50.3% YoY to 76.4 billion yen, including one-time items such as foreign exchange gains and gains on sale of cross-shareholdings.
Segment Results for FY2026/8 Full Year
Japan business: Revenue increased and operating profit grew by approximately 20%, driven by improved gross profit margin.
Operating revenue was 510.9 billion yen, up 8.7% YoY, and operating profit was 63.3 billion yen, up 21.6% YoY.
Operating revenue increased, driven by new store openings and seasonal promotional campaigns such as “MUJI Week,” “MUJI Good Price Festival,” and “Good Point Week.”
Full-year LFL store + EC sales were 102.4% YoY. EC sales fell below the previous year due to the system suspension in H1, but store sales performed strongly and total sales exceeded the previous year. Sales of all product categories, Apparel, Household goods, and Food, exceeded the previous year.
Operating profit increased. Gross profit margin improved, and operating profit margin improved by 1.3pp YoY to 12.4%.
East Asia business: Household goods and Food drove sales growth, with revenue increasing by more than 30%. Operating profit margin improved to 21.0%.
Operating revenue was 293.8 billion yen, up 32.2% YoY, and operating profit was 61.6 billion yen, up 44.2% YoY.
Operating revenue increased. Full-year LFL store + EC sales were 115.6% YoY, led by sales growth in Household goods and Food.
Operating profit increased. Gross profit margin improved, and SG&A expense/revenue ratio also declined alongside sales growth, resulting in an operating profit margin of 21.0%.
Mainland China business posted LFL store + EC sales of 116.3% YoY. In addition to strong performance in Household goods and Food driven by local merchandising, marketing initiatives and small-scale renovations also contributed to revenue and profit growth.
Taiwan business saw increased revenue and profit, driven by strong sales in Health and Beauty and Food, supported by expanded product lineup through strengthened local merchandising, as well as an improvement in discount rate.
Hong Kong business saw strong sales in Household goods and Food. SG&A expense/revenue ratio improved significantly, driven primarily by logistics structure improvement through warehouse relocation, contributing to revenue and profit growth.
Korea business saw an increase in customer traffic driven by strengthened marketing. Sales grew by more than 40%, with both stores and EC performing strongly. SG&A efficiency improvement also contributed to revenue and profit growth.
Southeast Asia and Oceania business: LFL store sales grew under a strengthened management structure. Combined with contributions from new store openings, revenue and profit grew significantly.
Operating revenue was 66.5 billion yen, up 32.8% YoY, and operating profit was 9.1 billion yen, up 64.1% YoY.
Operating revenue grew to 132.8% YoY, driven by store network expansion centered on flagship store openings in Thailand business and Vietnam business.
LFL store + EC sales were 108.7% YoY. Under a strengthened management structure, we accelerated improvements to the sales floor and focused on refining sales plans.
Operating profit grew to 164.1% YoY. Gross profit margin improved through restrained discounts and price reviews in certain markets, and SG&A efficiency improved alongside sales growth, resulting in an improved operating profit margin.
LFL store + EC sales posted double-digit YoY growth, particularly in Malaysia business, Vietnam business, and Australia business.
For Singapore business, while LFL store + EC sales decreased YoY due to price revisions and restrained discounts, profitability improved. In August 2026, LFL store + EC sales exceeded the previous year.
Europe and North America business: Despite upfront store opening expenses, both Europe business and North America business posted revenue and profit growth driven by LFL store sales growth.
Operating revenue was 52.2 billion yen, up 24.1% YoY, and operating profit was 8.0 billion yen, up 17.0% YoY.
Operating revenue increased, driven by LFL store + EC sales growth and the resumption of store openings in North America business. LFL store + EC sales were 111.8% YoY.
Operating profit increased to 117.0% YoY. However, SG&A/revenue ratio deteriorated due to upfront investment related to the resumption of store openings in North America business and flagship store openings scheduled in Europe business in FY27/8, resulting in an operating profit margin of 15.5%, down 0.9pp YoY.
Europe business posted double-digit LFL store + EC sales growth YoY through improved sales planning accuracy and expanded lineup. Revenue and profit increased despite upfront flagship store opening investment.
North America business grew, driven by strong sales in Household goods and Food, supported by expanded lineup. EC sales grew significantly, partly as a rebound from the EC warehouse relocation in FY25/8. Revenue and profit increased despite higher costs from logistics center relocation and resumption of store openings. Tariff refunds in the U.S. business also contributed.
Number of Stores: 1,486 stores (723 in Japan and 763 overseas)
For Japan business, the number of stores increased by 40 to 723 as we opened profitable stores mainly in suburbs.
For overseas business, the number of stores increased by 34 to 763, driven by expansion primarily in East Asia business and Southeast Asia and Oceania business.
For East Asia business, the number of stores increased by 22 to 579 through openings in mainland China business, Taiwan business, and Korea business.
For mainland China business, the number of stores increased by 11 to 433, as the scrap-and-build strategy continued alongside new store openings.
For Southeast Asia and Oceania business, the number of stores increased by 11 to 135. New stores were opened primarily in the Philippines business, Vietnam business, and Malaysia business.
For Europe and North America business, the number of stores increased by 1 to 49. We resumed store openings in North America business.
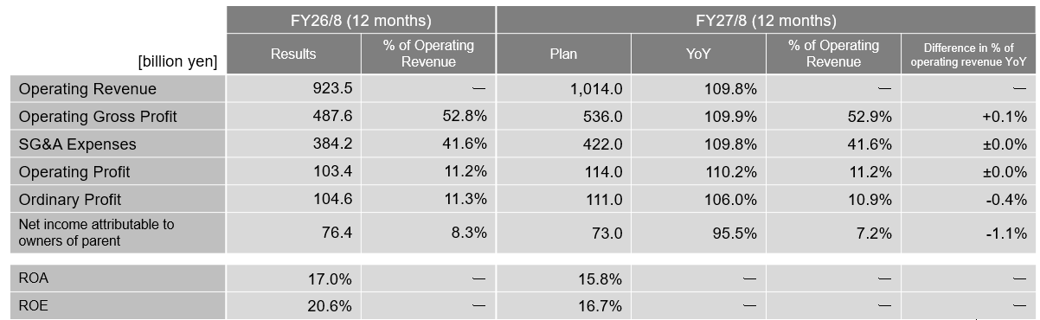
FY27/8 Consolidated Full-Year Plan: Operating revenue to exceed 1 trillion yen for the first time, with double-digit operating profit growth while continuing growth investments.
Operating revenue is expected to exceed 1 trillion yen, driven by LFL store sales growth and new store openings in Japan business and overseas business.
Despite continued pressure from less favorable hedged exchange rates resulting from yen depreciation and higher raw material costs, gross profit margin is expected to improve YoY, reflecting cost reductions through in-house production and a higher overseas business sales mix.
Upfront investment for overseas business will increase, while improvement of cost efficiency in Japan business is expected to keep the SG&A expense/revenue ratio broadly unchanged YoY. As a result, operating profit margin is projected at 11.2%.
Net income attributable to owners of parent is expected to decrease slightly due to the absence of one-time gains recorded in FY26/8, but is planned to increase excluding one-time factors.
LFL store + EC sales are planned at 104% YoY in Japan business, 107% in East Asia business (including 106% in mainland China business), 110% in Southeast Asia and Oceania business, and 106% in Europe and North America business.
The total number of stores as of the end of August 2027 is expected to reach 1,584, comprising 760 stores in Japan and 824 overseas. Japan business will open not only large suburban stores but also small-format stores in urban areas. Overseas business will resume openings in Europe and open stores across all regions.
Shareholder Returns – Dividend Plan: For FY26/8, an annual dividend of 38 yen per share is planned, an increase of 13 yen from FY25/8. Revised upward by 6 yen from the previous forecast.
The annual dividend per share for FY26/8 is planned to be 38 yen (interim: 16 yen, year-end: 22 yen), an increase of 13 yen from FY25/8.
The annual dividend per share for FY27/8 is planned to be 38 yen, the same as FY26/8 (interim and year-end: 19 yen each).
We will continue to generate cash centered on growth investment and provide stable dividends with a target payout ratio of 30%.
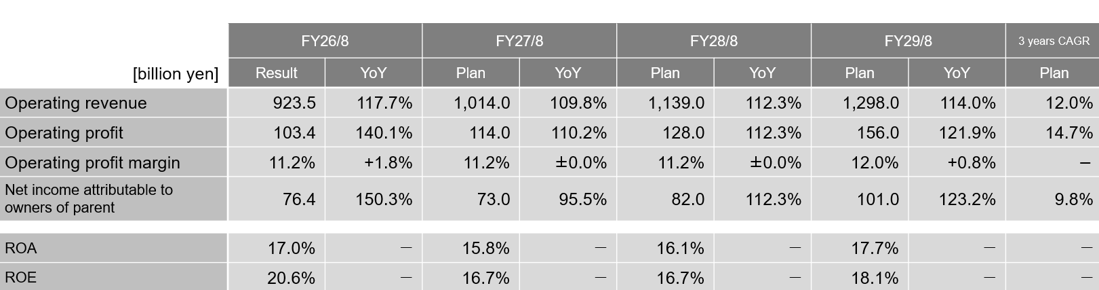
Updated 3 Year Rolling Plan: Aim to achieve operating revenue of approximately 1.3 trillion yen, operating profit of over 150 billion yen, and an operating profit margin of 12% in FY29/8.
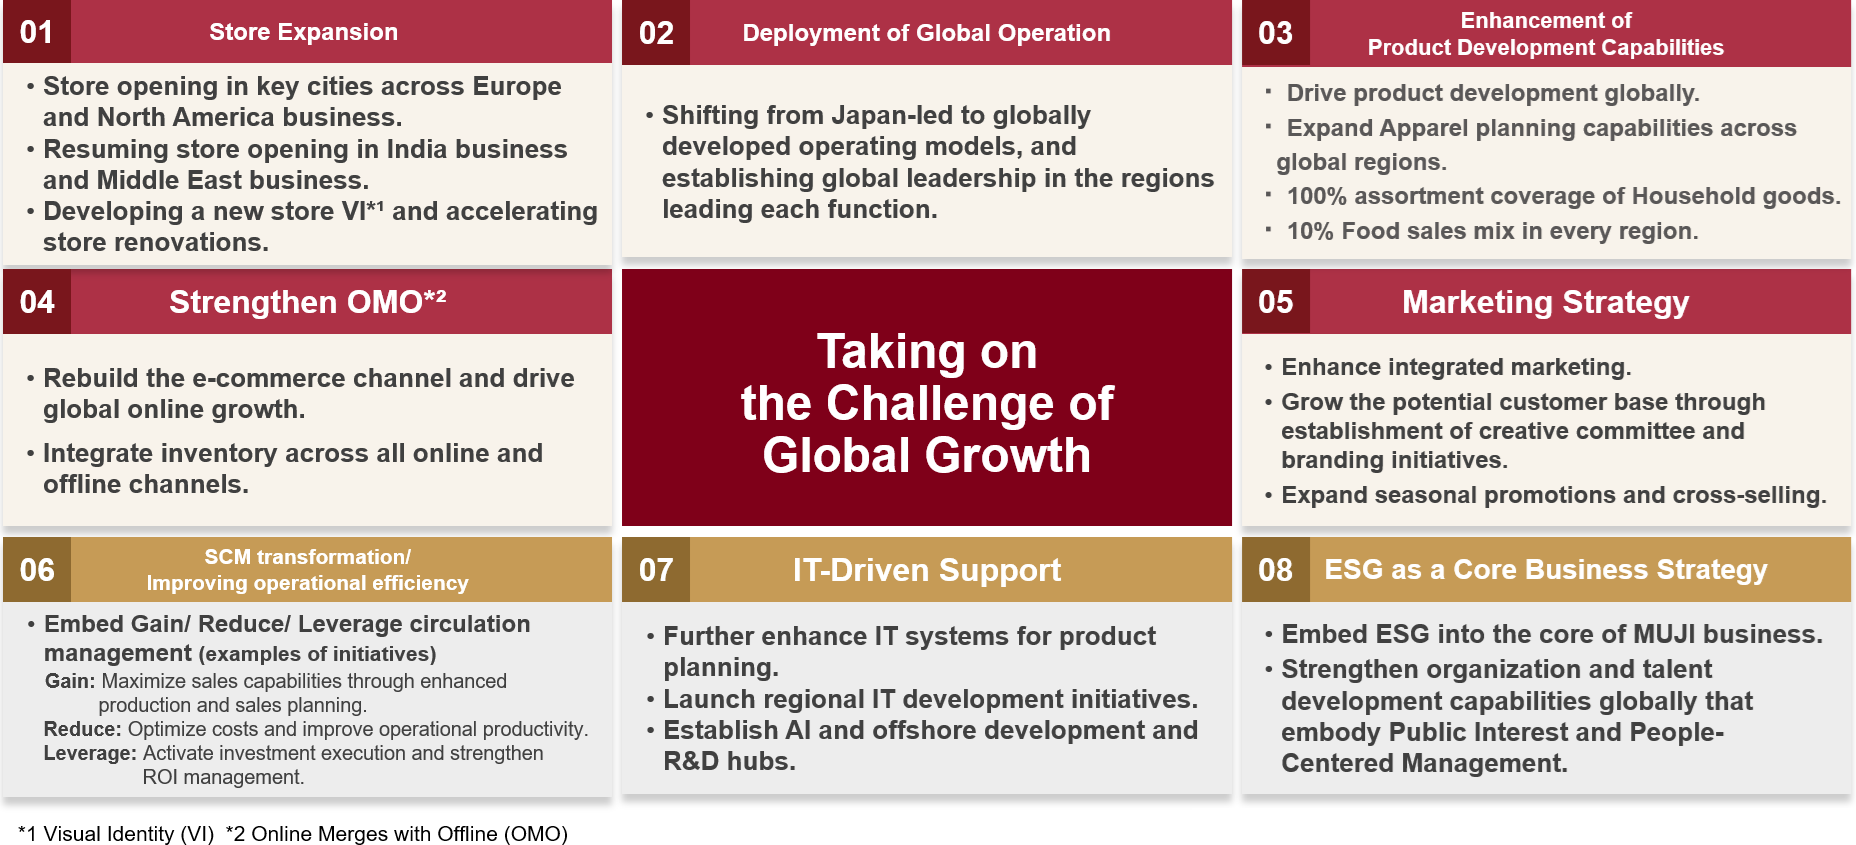
■Business Strategy Going Forward With the optimization phase complete, we are entering a new phase of bold yet disciplined challenges, supported by investments for global growth. 1.Accelerate strategic investments, primarily in Europe and North America business, to support store expansion and strengthen business foundations overseas. Continue to generate stable revenue and profits in Japan business and Asia businesses. Start to reallocate resources to build India business and the Middle East business into future profit-generating pillars. 2.Strengthen the global strategy team and promote a “Globe-Turning Perspective” to enable simultaneous growth around the world. 3.Realize the benefits of productivity initiatives and continue improving profit margins. 4.Based on growth impact and challenge-to-reward potential, the key priorities for the next medium-term plan are: (1) Expansion in Europe and North America business, (2) Productivity improvement, and (3) Talent development and utilization.
Based on FY26/8 results, we plan to achieve a CAGR of 12.0% in operating revenue and 14.7% in operating profit.
Through FY28/8, operating profit margin is expected to remain in the 11% range, reflecting upfront investments in Europe and North America business as well as the negative impact from less favorable hedged exchange rates resulting from yen depreciation. In FY29/8, we expect profit margins to improve, driven by contributions from Europe and North America business and an increase in overseas sales mix to more than 50%.
In Japan business, we aim to achieve stable growth and improve profitability through productivity improvement. In overseas business, we will accelerate growth through store expansion, with a focus on Europe and North America business, driven by both an increase in the number of stores and higher sales per store.
Three-year average YoY LFL store + EC sales are expected to be 102% in Japan business and 105% in overseas business, including 105% in mainland China business.
The total number of stores is expected to be 1,850 by the end of FY29/8. We plan an annual net increase of 45 stores in Japan business and 75 stores in overseas business, including 30 stores in mainland China business.
Although ROE is expected to decline in FY27/8 due to the absence of one-off gains recorded in FY26/8, we expect it to improve through FY29/8, supported by profit growth.